Bad credit loans in Kitchener run from $100 payday advances to $10000 installment loans, approved on employment income and banking rather than a credit score. This page explains what lenders actually read, gives honest odds by credit situation, and flags the upfront fee scams that chase borrowers with damaged files.
How Bad Credit Loans in Kitchener Get Approved
Bad credit loans in Kitchener are approved on what your chequing account shows, steady employment deposits from a full time or part time job, room to carry the repayment, and no fresh pile of bounced payments, with the credit score sitting last in that line.
The mechanism is the read only bank connection. In about a minute the lender sees your real pay pattern, and a file damaged in 2023 matters less than a paycheque that has landed every second Friday since spring.
The how it works page shows that verification step on screen. Nothing about it requires explaining your history to anyone; the deposits make the argument for you.
What the Bank Check Shows a Lender
The bank check shows deposit size, deposit rhythm, existing loan payments and NSF activity for roughly the last 90 days, and those four lines carry the decision.
Two files with the same 540 score read very differently. One shows a $1700 biweekly plant deposit and clean months; the other shows the same deposit with three bounced debits in October. The first gets an offer, the second usually waits a cycle.
That 90 day window is useful to know. A rough autumn stops hurting by February, so when the recent months are the problem, the strongest move is often six clean weeks before applying rather than a stack of hopeful applications now.
Check your options on today's income
What the Score Bands and R Ratings Mean
A score under 600 is the zone where most banks decline unsecured lending, which is descriptive, not a verdict on you; income based lenders work that zone every day.
| What the file shows | What it means | Who still lends |
|---|---|---|
| Score 600 or above | Banks may approve with conditions | Banks, credit unions, online lenders |
| Score under 600 | Most banks decline unsecured credit | Income based online lenders |
| R7 on an account | Repaid through a consumer proposal | Payday and some installment lenders |
| R9 on an account | Written off or bankruptcy | Payday lenders, slowly installment again |
R ratings describe single accounts, not the person. R1 means paid as agreed, and a file can carry an old R9 beside two years of new R1 lines, which is exactly the mix rebuilding produces.
Pull your own file before assuming the worst. Both bureaus give Canadians free access, and plenty of Kitchener applicants discover the damage is one old phone bill in collections rather than the wreckage they imagined, which changes which lenders are worth approaching first.
The Payday Route Skips the Bureau
A payday loan approves without pulling the credit file at all, which is why it stays open to borrowers carrying an R9: the decision runs on deposits, the amount is capped at 50% of net pay, and the cost is capped at $14 per $100.
The trade is the single debit. Up to $1500 plus the fee leaves on your next pay date, which a damaged budget feels hard. The payday loans page prices every amount in a table before you consider it.
The Installment Route Prices the Risk Instead
Installment lenders do pull the file, then price the risk inside 18% to 35% APR rather than declining it, so a bruised file typically lands near the top of the band on $500 to $10000 over 3 to 60 months.
Most of them also report payments, which makes this the route that repairs the file while it carries the expense. The installment loans page works the monthly payments at a representative rate.
Honest Approval Odds for Bad Credit Loans in Kitchener
Approval odds for bad credit loans in Kitchener run on income: steady deposits with a clean recent stretch approve often, thin or irregular deposits approve small or wait, and no employment deposits approve nowhere legitimate, whatever an ad promises.
A discharged consumer proposal with a year of steady plant pay is a routine file for bad credit loans in Kitchener. A strong salary two weeks into a new job often waits until the first deposits land. Nobody honest quotes a percentage without seeing the account.
Be suspicious of certainty in either direction. A lender who approves everyone is recovering losses in ways you will not enjoy, and a bank that declines you is pricing policy, not reading your kitchen table.
The Kitchener-Waterloo Situations That Bring People Here
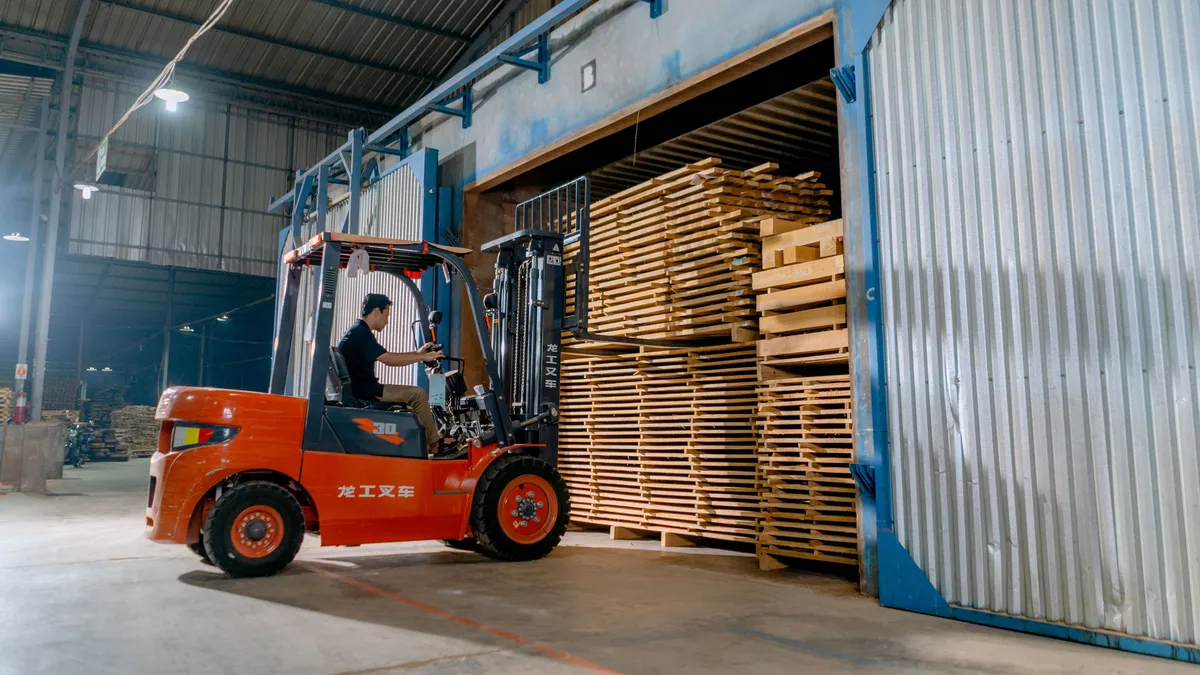
The common local trigger is income that stepped down before the bills did: a temp agency placement ending once the Christmas shipping peak clears the warehouses, serving hours thinning in the weeks after Oktoberfest wraps, or a new plant job whose first full cheque is still ten days out.
White collar files show up too. Contract roles at the tech offices around the old tannery district end and restart, and a household carrying a mortgage sized for two incomes bridges the restart gap on one.
In every version, the deposits tell the story the score cannot: the income exists, it stumbled, and it resumes on a date the lender can see.
Timing the application to that story helps. A warehouse recall letter or a signed offer from the new plant does nothing for a payday file, but two deposits from the new job change everything, so the strongest application is often ten days after the restart, not the day the panic peaks.
Rebuilding Steps That Actually Move the File
Rebuilding comes down to new on time entries stacking on top of the old damage until the file reads current, and four moves do most of that work.
- Stop the bleeding first: no new NSF returns, even if that means cancelling subscriptions the day before payday.
- Put one reportable payment on the file, a small installment loan or a secured card, and never miss it.
- Pull your own report from both bureaus and dispute anything that is not yours; errors are common after collections.
- Keep old positive accounts open, since file age is part of the score.
Give it quarters, not weeks. Files that carry an R7 read noticeably better after a year of clean entries, which also moves future offers toward the cheap end of the band.
Local free help exists while you do it. Non profit credit counselling agencies serve the region and will read a budget with you at no charge; what they cannot do is lend, so treat anyone charging hundreds up front to repair a score as the scam section below describes.
The Upfront Fee Scam Wears a Kind Voice
No legitimate lender charges a fee before funding, and that single rule filters almost every scam aimed at damaged credit files: the deposit to release your loan, the processing fee by gift card, the first payment in advance.
Real lenders are licensed through Consumer Protection Ontario, take their fee inside the regulated cost of the loan, and never ask for banking passwords in chat. The Financial Consumer Agency of Canada keeps plain guidance on spotting the fakes.
Pressure is the tell. A borrower with options gets time to read; a mark gets a countdown. The Loans Kitchener homepage lists what a licensed offer must disclose before you sign anything.
Apply with licensed lenders onlyBad Credit Loans Kitchener FAQ
Does applying hurt my score further?
A payday application does not touch the bureau. Installment applications usually run a soft check first, then one hard pull if you accept an offer. What genuinely grinds a score down is a burst of hard pulls across many lenders in one week.
I am two years past a bankruptcy discharge. What can I realistically get?
With steady employment deposits, payday amounts are routine and small installment offers are realistic, usually $500 to $2000 at the upper end of the rate band. Each repaid loan improves the next offer; the discharge date matters less every quarter.
My partner has the good file. Should we apply together?
Only if the loan truly needs the second income, because a joint application puts both names on the debt and any missed payment lands on both files. Many couples keep bad credit loans in Kitchener in one name to protect the stronger file.
Will a collection account stop an approval?
Not by itself. Income based lenders care whether the collection is being paid or ignored and whether current deposits carry the new payment. An old collection with clean recent banking reads far better than a clean file with bounced debits last month.
Why was I declined when a friend with worse credit got approved?
Because the decision ran on banking, not on the scores you compared. Different deposit size, a payday loan still open, or a cluster of recent NSF returns will separate two files that look identical from the outside.
Loan options in Kitchener
One page per product: who qualifies, how fast it funds and what to check before you sign.